Resource Architecture

Asset Planning Framework

Gain complete clarity over your entire balance sheet. Organize tangible assets, liquid reserves, and compounding investments into a synchronized financial engine.

Methodology

The 5-Stage Asset Planning Lifecycle

A disciplined step-by-step roadmap to align your existing wealth with future personal ambitions.

Stage 01

Identify

Catalog every bank balance, property asset, pension holding, and liability in one clear register.

Stage 02

Organize

Classify capital by accessibility, liquidity tier, operational purpose, and volatility profile.

Stage 03

Prioritize

Establish emergency reserves first, followed by short-term obligations and multi-decade wealth targets.

Stage 04

Allocate

Distribute capital across balanced asset classes calibrated to your risk tolerance and horizon.

Stage 05

Review

Conduct regular quarterly balance audits to rebalance assets and accommodate life updates.

Capital Segments

Core Asset Categories In Detail

Understanding the unique role, liquidity characteristics, and risk profile of each financial asset class.
Liquid Savings

Savings & Cash Liquidity

Guaranteed principal vehicles providing immediate access for daily living and unforeseen expenses.

High-yield savings accounts
Checking and operational float
Short-duration certificates
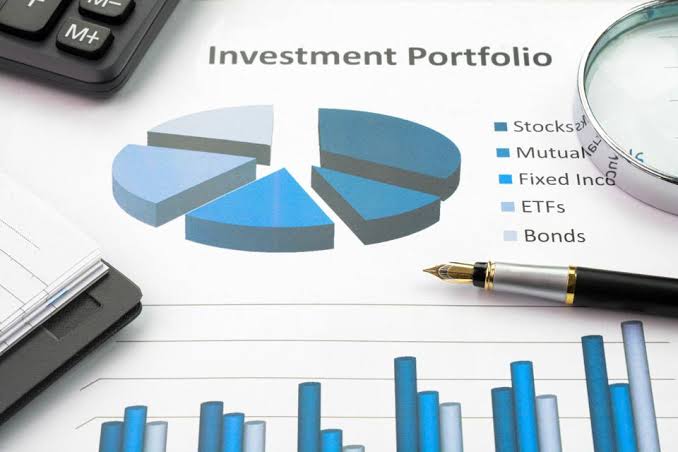
Investment Portfolios

Growth & Market Investments

Assets designed to outpace inflation and generate long-term compounding returns through broad markets.

Broad index funds & ETFs
Global sovereign bonds
Dividend-producing equities
Property and Real Assets

Real Estate & Tangible Assets

Illiquid but foundational real properties that provide utility, shelter, and long-term capital preservation.

Primary residence equity
Real estate investment trusts
Physical capital equipment
Retirement Reserves

Retirement Resources

Tax-favored accumulation vehicles structured to sustain post-career independence and healthcare security.

Tax-deferred retirement accounts
Employer matched plans
Defined-benefit annuities
Financial Reserves

Defensive Financial Reserves

Dedicated risk mitigation capital designed to absorb emergencies without triggering asset liquidations.

6-month living expense reserve
Comprehensive insurance buffers
Opportunistic liquid cash
Financial Priorities

Strategic Cash Flow

Monthly surplus management that funnels incoming revenue systematically into respective asset buckets.

Automated monthly contributions
Debt amortization schedules
Excess income rebalancing
Organization Matrix

The Financial Organization Board

Bridging current resources with immediate life needs and ultimate wealth aspirations.

Current Resources

What you currently control

Liquid Cash Reserves

Immediate funds held in high-yield savings accounts.

Active Investment Holdings

Taxable brokerage portfolios and index allocations.

Retirement Balances

Accumulated workplace plans and individual accounts.

Fixed Real Assets

Residential equity and physical properties.

Financial Needs

What must be sustained

Essential Living Expenses

Housing, sustenance, transport, and utilities.

Debt Service & Amortization

Eliminating high-interest liabilities systematically.

Emergency Risk Buffers

Protecting household against unexpected disruptions.

Insurance Protection

Hedging against catastrophic health or property loss.

Future Goals

What you are building toward

Financial Independence

Passive portfolio yields covering full living requirements.

Major Capital Acquisitions

Home purchases, business expansions, and ventures.

Higher Education Funds

Funding family advanced degree pathways and endowments.

Legacy Preservation

Intergenerational wealth transfers and estate durability.

Action Checklist

The Asset Planning Checklist

Follow these proven steps to establish a balanced and organized financial foundation.

Review Financial Resources

Perform an honest comprehensive audit of all accounts, balances, and debts at least once per quarter.

Identify Strategic Priorities

Separate urgent short-term needs from optional desires and long-term compounding milestones.

Establish Savings Goals

Automate monthly contributions directly into separate high-yield accounts for specific milestones.

Consider Time Horizons

Never expose short-term funds (< 3 years) to market volatility; keep long-term assets invested.

Understand Risk Profiles

Maintain an asset allocation that lets you sleep peacefully during normal market fluctuations.

Review Strategy Periodically

Rebalance your portfolio annually to maintain intended risk parameters as valuations shift.

FAQs

Asset Planning Questions

Common questions regarding asset categorization and resource distribution.

How much should I keep in liquid cash reserves?

Most financial planners suggest keeping between 3 to 6 months of essential living expenses in high-yield, easily accessible savings accounts to cushion against unforeseen shocks.

How often should I rebalance my asset allocations?

An annual or semi-annual review is typically sufficient. Rebalancing ensures that outperforming assets don't unintentionally skew your portfolio into higher risk tiers.

What is the difference between tangible and financial assets?

Tangible assets possess physical form (such as real estate or vehicles), whereas financial assets (such as stocks, bonds, and bank deposits) derive their value from contractual claims.

Need Guidance on Structuring Your Assets?

Connect with our team to learn more about our strategic frameworks and planning principles.